The Autumn Budget 2026, scheduled for 28 October, will test whether Chancellor John Healey can support recruitment and workforce investment while meeting growing demands on public spending. For employers, the consequences will extend beyond tax rates to minimum pay, training, employee finances and the resources available to enforce employment rights.
In Brief
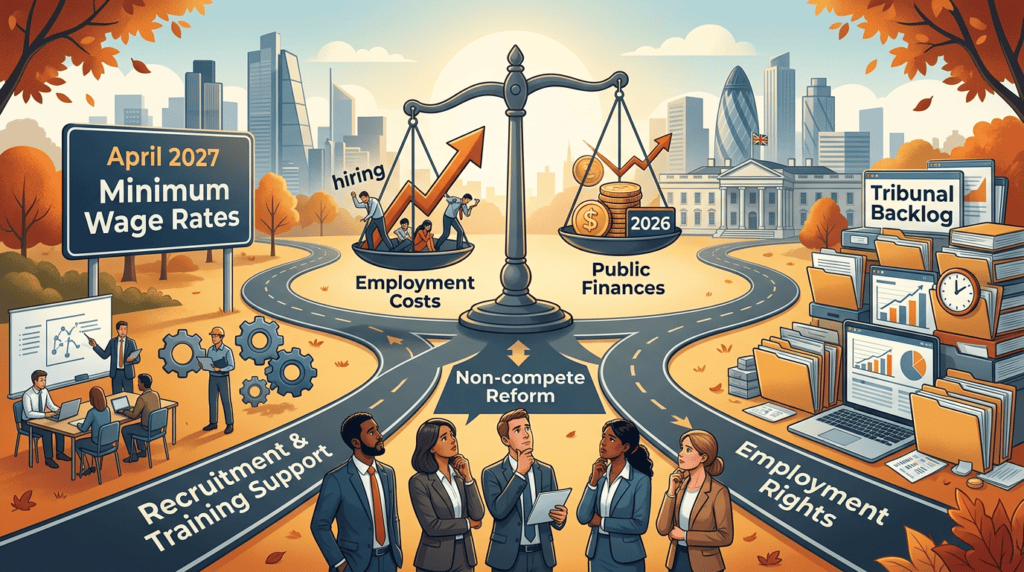
The Autumn Budget 2026 arrives amid weak hiring, rising employment costs and pressure on public finances. For employers, the main questions concern April 2027 minimum wage rates, possible recruitment and training support, and the Government's plans for non-compete reform. The employment tribunal backlog adds a further challenge as significant changes to employment rights take effect.
Key Points
- Employment and inflation: Payrolled employment rose by 13,000 between July and September, but vacancies fell to 691,000, their lowest level since early 2021, with smaller firms citing higher labour costs as a reason for holding back recruitment. The Bank of England expects inflation to rise slightly above 4% in early 2027.
- Minimum wage increases: The Autumn Budget 2026 is expected to confirm the April 2027 National Minimum Wage and National Living Wage rates. The Low Pay Commission's indicative National Living Wage range is £13.02–£13.34 an hour, with a central estimate of £13.18, although the final rate may differ.
- National Insurance and recruitment: The Government has rejected extending existing employer National Insurance relief to all under-25s. Support already available includes up to £2,000 for eligible non-levy employers in England recruiting new apprentices aged 16–24, alongside a separate £3,000 Youth Jobs Grant, subject to eligibility conditions.
- Skills and training: Employers' training expenditure in England fell by 19% in real terms between 2011 and 2024, equivalent to £10.6 billion. The Autumn Budget 2026 could provide further support for apprenticeships and workforce development, although additional funding has not been confirmed.
- Employment rights and tribunals: Employment tribunals had around 70,000 open single claims at the end of June 2026. From January 2027, the qualifying period for ordinary unfair dismissal protection is due to fall to six months, and the cap on compensatory awards is due to be removed, which is likely to add to pressure on tribunal resources.
- Non-compete reform: The Prime Minister announced on 9 October that the Government will legislate to restrict non-compete clauses, with further details expected alongside the Autumn Budget 2026. According to the Startup Coalition, the Government will also outline a consultation timetable on wider restrictive practices, including lengthy notice periods and potentially garden leave. Existing restrictions remain subject to current law until any changes take effect.
- Public spending and taxation: The OBR's March 2026 forecast projected health and disability benefit spending of £109.8 billion by 2030–31. Updated forecasts accompanying the Autumn Budget 2026 will inform decisions on taxation, public spending and the scope for additional recruitment, training and employment support.
Ahead of the Autumn Budget 2026, several measures are being proposed to ease the pressures facing employers, although the Government has yet to confirm which, if any, it intends to introduce.
A Fragile Recovery in Jobs and Pay
Resolution Foundation analysis found that payrolled employment increased by 13,000 between July and September, following a decline of 194,000 between October 2024 and July 2026. Private-sector pay growth also strengthened to an annualised three-month rate of 4.3%.
That figure is not the year-on-year increase. The ONS earnings release puts annual private-sector regular pay growth at 3.0% for June–August. Across the economy, regular earnings increased by just 0.6% after inflation, using the measure that includes owner-occupiers' housing costs.
Recruitment demand nevertheless remains weak. ONS estimates show that vacancies fell by 21,000 to 691,000 in July–September 2026, taking the total below 700,000 for the first time since February–April 2021. The decline was mainly among smaller firms, which continued to cite higher labour costs as a reason for holding back recruitment.
The Autumn Budget 2026 therefore arrives before employees have experienced a substantial improvement in purchasing power. In September, the Bank of England projected that inflation would rise slightly above 4% in the first quarter of 2027, as reported in the Commons Library's briefing. Employers may consequently face continuing pressure over pay and retention despite only tentative improvements in recruitment conditions.
April 2027 Minimum Wage and Living Wage Announcement
The Autumn Budget 2026 is expected to include the announcement of the new National Minimum Wage and National Living Wage rates applying from 1 April 2027. These will determine minimum hourly pay for different age groups and eligible apprentices. The new rates have not yet been confirmed.
The Low Pay Commission's April consultation estimated that maintaining the National Living Wage at two-thirds of median earnings would require an hourly rate of between £13.02 and £13.34 from April 2027. Its central estimate was £13.18, a 3.7% increase. These were indicative figures, not confirmed recommendations, and the final rate may differ.
The Low Pay Commission's remit asks for recommendations by the end of October. The Government remains committed to aligning the 18–20 rate with the National Living Wage, but the pace and timing remain subject to the Commission's assessment of employment prospects.
The announcement will be particularly important for employers with large numbers of lower-paid staff. Any increase could affect not only their wage bills and employer National Insurance contributions, but also pay differentials between entry-level and more experienced employees. As with the previous National Minimum Wage and National Living Wage increases, employers will need to review their pay structures and update payroll arrangements ahead of April 2027.
National Insurance and Youth Recruitment
Employment costs are a central issue for the Autumn Budget 2026. Under current National Insurance rules, employers generally pay 15% on earnings above £5,000 annually, subject to applicable reliefs. A zero rate already applies to employees under 21 and qualifying apprentices under 25 on earnings up to £50,270 annually. Eligible employers can also reduce their annual bill by up to £10,500 through the Employment Allowance. The impact of any change therefore depends on the workforce and existing reliefs, not simply the headline rate.
The British Chambers of Commerce has called for a cut in employer National Insurance contributions for workers under 25 to encourage recruitment. Separately, the Work and Pensions Committee recommended extending the existing relief to all employees under 25 at the same earnings threshold of £967 a week, or £50,270 a year. The Government rejected that recommendation in its response to the Work and Pensions Committee, published on 15 October 2026.
Targeted support is already available. Under the apprenticeship funding rules, eligible non-levy-paying employers in England can receive up to £2,000 for recruiting qualifying new apprentices aged 16–24 whose training starts from 1 October 2026. The apprentice must have started work with that employer no more than 90 days before their apprenticeship training begins. For eligible starts from 1 August 2026, the Government also covers their apprenticeship training and assessment costs up to the funding-band maximum.
The Youth Jobs Grant offers £3,000 to employers hiring eligible 18–24-year-olds who have been receiving Universal Credit and looking for work for at least six months. It is paid in two instalments: £1,800 after six weeks and £1,200 after 18 weeks, provided the grant conditions are met. These payments can be combined with apprenticeship incentives where the separate eligibility conditions are met. Any further support announced in the Autumn Budget 2026 would build on these existing schemes.
Will the Autumn Budget 2026 Support Training?
Lower recruitment costs cannot, by themselves, supply missing skills. Skills England's annual skills report records a 19% real-terms fall in employers' training expenditure in England between 2011 and 2024, equivalent to £10.6 billion. Smaller employers also face difficulties navigating provision and committing staff to longer programmes.
As our recent article on skills shortages explained, favouring experienced recruits while reducing entry-level opportunities can make it harder to develop the next generation of skilled workers.
The Autumn Budget 2026 offers an opportunity to strengthen training provision and make support easier to use. The practical test is whether funding helps employers release staff to learn, access suitable courses and develop capabilities that recruitment alone cannot supply. Further-education provision and support for workplace supervision also matter: a funded training place is useful only if an employer can make it work in practice.
Overseas hiring also has limits. The Skilled Worker route usually requires an annual salary of at least £41,700 or the occupation's going rate, whichever is higher, although exceptions apply. Employers should assess training and sponsorship options together rather than assume that either offers an immediate solution.
Employment Rights Need a Functioning Tribunal System
Tribunal capacity is another important test for the Autumn Budget 2026. Ministry of Justice statistics recorded 70,000 open single claims at the end of June. During April–June, tribunals received 14,000 single claims but disposed of only 6,100.
The Ministry of Justice cautions that the open caseload figures may include an overcount of around 3% for single cases and lead multiple cases following changes to its data systems.
As our report on the employment tribunal backlog highlighted, unresolved disputes create uncertainty for both employees and businesses.
The Employment Rights Act 2025 will bring significant changes to unfair dismissal protection. According to the Government's implementation timetable, the qualifying period will fall from two years to six months for dismissals taking effect from 1 January 2027, when the cap on compensatory awards will also be removed. The normal time limit for bringing most employment tribunal claims has already increased to six months minus one day from 1 October 2026, subject to transitional provisions and exceptions. With a substantial backlog already affecting the tribunal system, the Autumn Budget 2026 presents an opportunity to provide the additional funding, judicial resources and administrative support needed to accommodate these reforms and reduce delays in resolving workplace disputes.
For employers, the changes will place greater importance on managing probationary periods, performance concerns and dismissals fairly and consistently. With employees gaining unfair dismissal protection sooner and having longer to bring most tribunal claims, employers should ensure that appropriate procedures are followed and employment decisions are properly documented.
Non-Compete Reform and Employee Mobility
As we reported in our recent article on non-compete clauses, Prime Minister Andy Burnham announced on 9 October that the Government intends to legislate to make it easier for employees to change jobs and for start-ups and growing businesses to recruit experienced workers. Further details are expected alongside the Autumn Budget 2026, with the Startup Coalition reporting that the Government will also outline a timetable for consultation on wider restrictions, including lengthy notice periods and potentially garden leave.
Until any changes are made, non-compete clauses remain subject to the existing common-law rules on restraint of trade, and employers and employees must continue to comply with their contractual obligations.
Funding the Autumn Budget 2026
The Chancellor faces difficult decisions in relation to the Autumn Budget 2026 over how to fund public services while supporting economic growth and avoiding further pressure on businesses and taxpayers. The Institute for Fiscal Studies has outlined a scenario in which an additional £35 billion of departmental spending could be required by 2030–31 to meet defence and health spending ambitions, protect other public services from real-terms cuts and accommodate pay and productivity pressures.
These challenges are compounded by the rising cost of welfare benefits, an issue we examined extensively in our earlier article on welfare benefits reform and the Government's back-to-work strategy. In its March 2026 forecast, the Office for Budget Responsibility projected that spending on health and disability benefits would rise from £76.9 billion in 2024–25 to £109.8 billion in 2030–31. Updated forecasts will accompany the Autumn Budget 2026 on 28 October. Although welfare payments fall outside departmental spending budgets, their continued growth adds to the wider pressure on public finances. Controlling expenditure while supporting those who can return to employment remains a significant challenge for the Government.
Against this backdrop, ministers face pressure to raise additional revenue without discouraging investment or employment growth. One possibility reportedly under consideration is an increase in the surcharge on bank profits from 3% to 8%, although no decision has been announced. The Autumn Budget 2026 will therefore need to balance competing spending priorities, the growing welfare bill and the need to maintain business confidence, while determining how much additional support can realistically be provided for recruitment, training and employment services.
The Wider Test for the Autumn Budget 2026
The Autumn Budget 2026 comes at a difficult time for the Government, with pressure to control public spending while encouraging investment, employment and economic growth. Rising welfare expenditure, persistent skills shortages and the cost of employment law reforms all add to the challenge of balancing the public finances without placing further burdens on businesses and households.
The success of the Autumn Budget 2026 will depend not simply on individual tax or spending announcements, but on whether the measures provide a credible foundation for stronger economic growth. Supporting employment and workforce development, improving productivity and ensuring that public services can meet growing demand are closely connected objectives.
Ultimately, the Autumn Budget 2026 will be judged by whether the Government can reconcile these competing priorities and create the conditions for sustainable growth, higher living standards and a stronger labour market.
Employers: What This Means
The Autumn Budget 2026 could affect payroll costs, recruitment decisions and workforce planning. Employers should prepare now for changes already scheduled and assess any new measures once their details and eligibility conditions are confirmed.
- Review payroll budgets: Model the cost of the April 2027 minimum wage increases, including the effect on employer National Insurance contributions and pay differentials. The Low Pay Commission's indicative range covers only the National Living Wage, so employers with younger staff should also consider the possibility of a larger percentage increase in the 18–20 rate, given the Government's commitment to align it with the National Living Wage. With inflation forecast to exceed 4% in early 2027, wider pay reviews may also come under pressure.
- Check recruitment and training support: Confirm eligibility before including incentives in recruitment budgets. The £2,000 apprenticeship payment is available to eligible non-levy employers in England recruiting new apprentices aged 16–24 who joined no more than 90 days before their training starts. The £3,000 Youth Jobs Grant is paid in two instalments, after six and 18 weeks, provided the grant conditions are met. Existing employer National Insurance reliefs for under-21s and qualifying apprentices under 25 remain available.
- Prepare for unfair dismissal changes: The six-month qualifying period will apply to dismissals taking effect on or after 1 January 2027. It will therefore cover existing employees with six months' service on that date, as well as dismissals decided in late 2026 where employment ends on or after 1 January 2027. Review probationary periods, performance management and dismissal procedures now, and make sure managers understand them. Keep clear records: the normal time limit for most tribunal claims has already increased to six months minus one day, subject to transitional provisions and exceptions.
- Monitor further Budget announcements: Following the Autumn Budget 2026, check the eligibility conditions and start dates of any new recruitment or training measures. Employers that use non-compete clauses, long notice periods or garden leave should follow the proposed reforms and identify where they rely on these restrictions. They should wait for the details before making wholesale changes. Existing non-compete clauses can be enforced only where their restrictions are no wider than reasonably necessary to protect legitimate business interests.

